SK hynix Shelves Solidigm IPO but Confirms New US Fab Plan
SK hynix has dropped plans to list its enterprise SSD subsidiary Solidigm, citing unfavorable stock markets. It confirmed it will still build a new factory in the United States.
 Merhabyte Newsdesk · · 2 min read
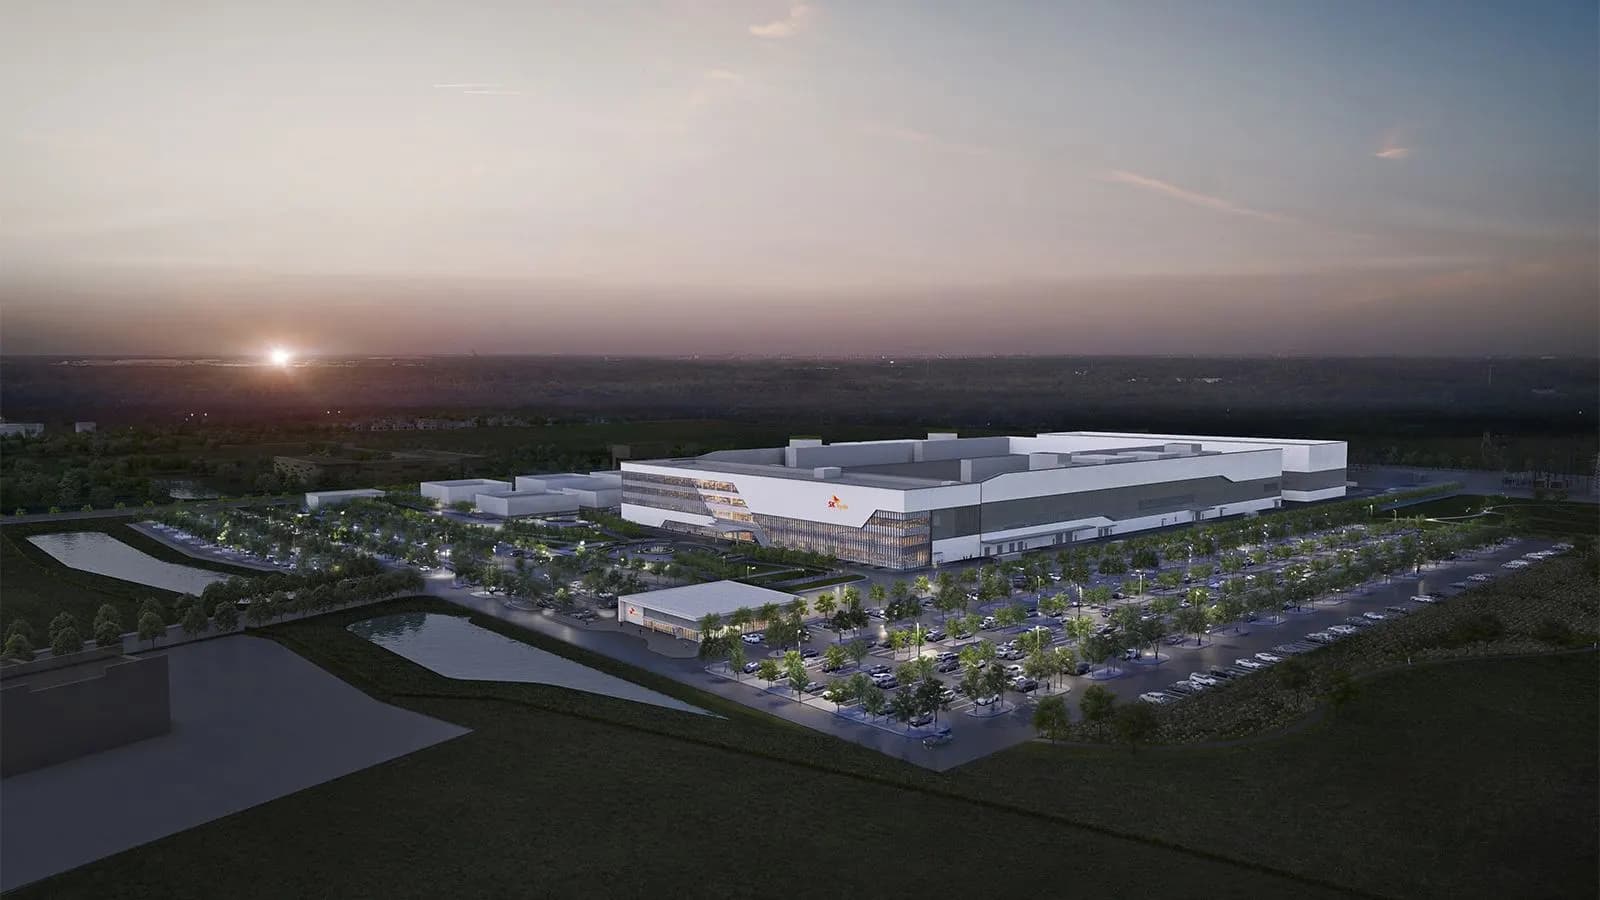
SK hynix has announced that it is abandoning plans to take its US-based enterprise SSD subsidiary, Solidigm, public. According to the company, the decision stems from unfavorable conditions in equity markets and the recent performance of semiconductor stocks.
In the same statement, SK hynix confirmed that it will build a new factory in the United States for Solidigm. The IPO is off the table, but the expansion remains a priority. The facility's capacity, investment amount and construction timeline have not yet been disclosed.
Why the IPO was shelved
SK hynix said it had weighed several options for financing capacity expansion, including direct investment, a pre-IPO fundraising round and an IPO. An offering could have raised capital from outside investors without adding to the company's debt. The company also argues that Solidigm's true value is not fully reflected in SK hynix's own market capitalization, and a listing could have made that value visible. Proceeds could have gone toward the expansion as well as dividends, share buybacks and share cancellations.
However, rising market volatility and a continuing correction in chip stocks made an IPO less attractive, according to SK hynix. The company contends that, under current conditions, it could not reach a valuation that adequately reflects Solidigm's growth prospects. It has therefore ended its evaluation of both the IPO and pre-IPO financing, though it says it will keep examining alternative funding methods.
The demand behind the US factory
Solidigm specializes in high-capacity data center SSDs built on floating-gate 3D QLC NAND. As AI infrastructure spending accelerates, demand for high-capacity storage is rising with it. Solidigm's current production capacity can barely meet its projected needs, and SK hynix believes the subsidiary requires additional manufacturing facilities in the US.
Such a plant could also strengthen SK hynix's manufacturing footprint in America, which matters given current trends toward bringing production onshore.
Possible reasons for walking away
At a time when enterprise SSD demand is at record levels and expected to climb further over the next few years, giving up a funding route that could raise billions of dollars raises questions. Building a modern 3D NAND fab costs tens of billions of dollars, and outside financing could have eased the strain on SK hynix's balance sheet and freed capital for other projects.
What follows is interpretation, not the company's statement: Solidigm's exceptional profitability may explain the choice. Micron's enterprise storage unit reportedly posted a non-GAAP gross margin of around 90 percent recently, while Solidigm, together with its parent, is said to hold 21.1 percent of the enterprise SSD market. Because Solidigm sells specialized products, its margins could be even higher. If margins like these hold for the next two to three years, Solidigm could substantially lift SK hynix's consolidated profitability and generate significant cash for future investment. SK hynix could then fund the US expansion with a mix of internal cash and borrowing, without giving up equity. Paying entirely in cash might be possible, but given the capital demands of today's chip fabs, it looks less likely. Either way, keeping full ownership of a highly profitable subsidiary, rather than selling part of it at a valuation the company considers too low, appears a natural choice for SK hynix.